Behavioral Finance vs Financial Psychology
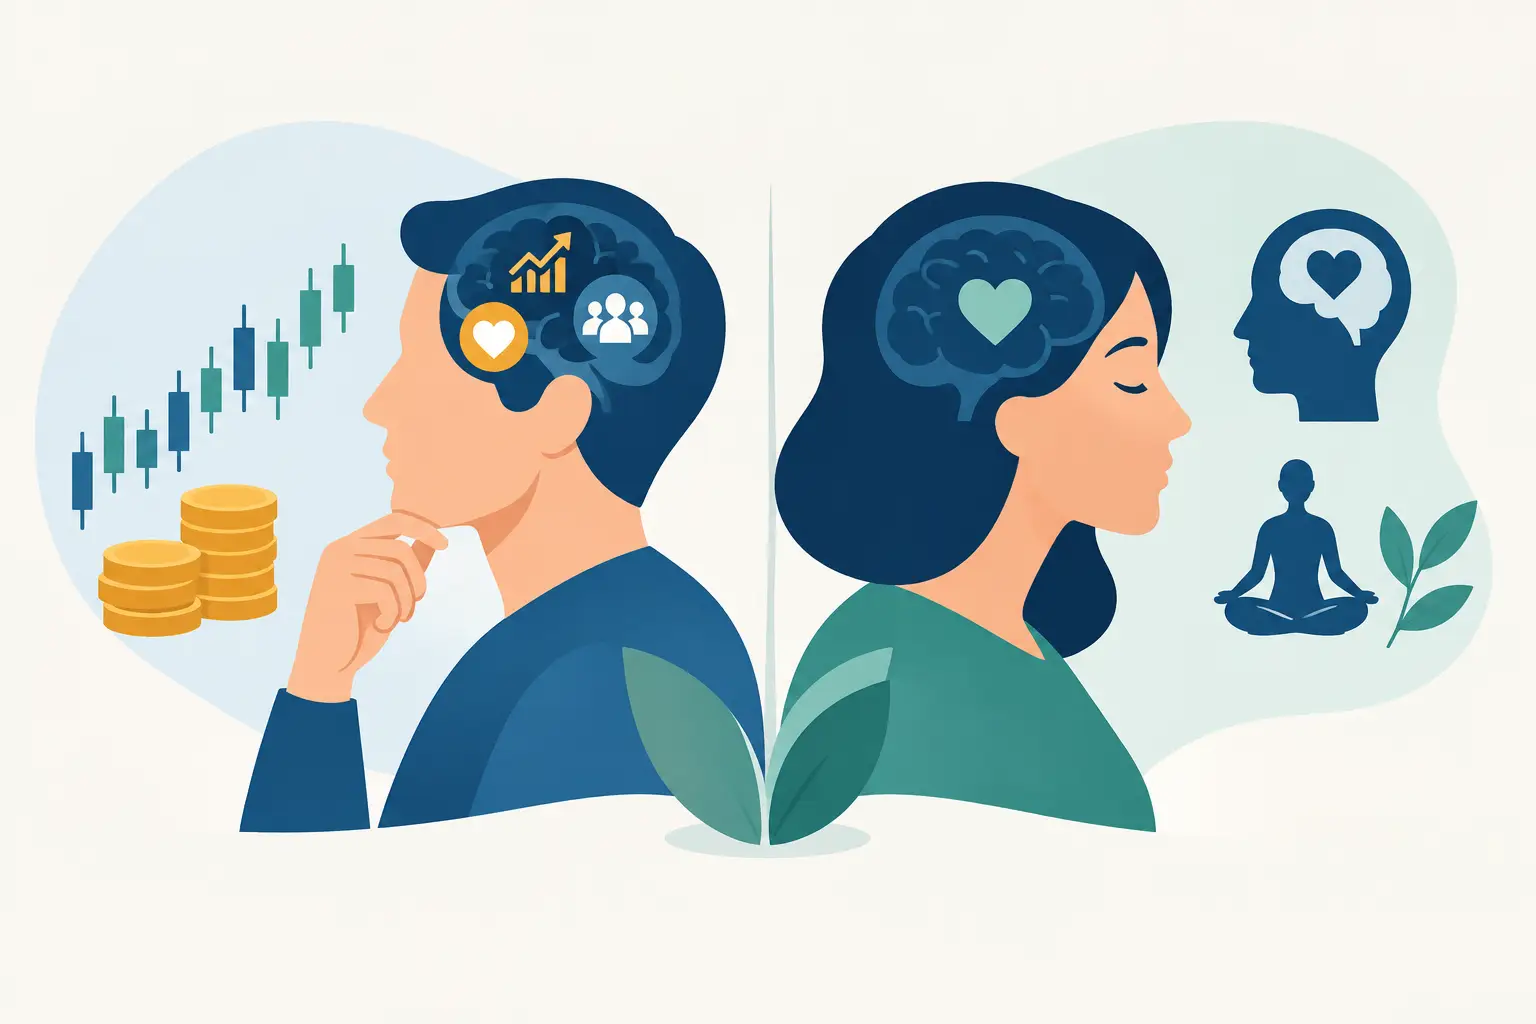
You can know that carrying a credit card balance is expensive and still avoid opening the statement. You can earn more than you did five years ago and still feel behind. You can make a careful investment plan, then abandon it during a market drop. Behavioral finance vs financial psychology is not an academic distinction when these moments shape your life. It is a useful way to understand whether you are looking at a decision error, the forces around it, or the deeper story that keeps producing it.
Both fields challenge the old assumption that people make money decisions logically. But they ask different questions, work at different levels, and point toward different kinds of change. Knowing the difference can help you move beyond advice that is technically sound but personally hard to follow.
Behavioral Finance vs Financial Psychology: The Core Difference
Behavioral finance studies how real people depart from the rational decision-making models often used in traditional economics and investing. It maps predictable mental shortcuts, emotional reactions, and social influences that affect financial choices. Its central question is often: What patterns cause people to make systematically imperfect decisions?
Financial psychology looks more closely at the individual behind the choice. It explores how beliefs, early experiences, identity, emotions, relationships, and perceived safety shape a person's relationship with money. Its central question is: Why does this particular pattern make sense to this person, even when it creates problems?
Think of someone who sells investments after a downturn. Behavioral finance may identify loss aversion, the tendency to feel a loss more intensely than an equivalent gain. It may also point to recency bias, where recent bad news feels more predictive than it really is. Financial psychology asks what the loss represents. Does it trigger a childhood memory of instability? Does investing feel reckless because security has always meant holding cash? Does a loss feel like proof that the person is irresponsible or incapable?
Neither lens is more legitimate. Behavioral finance gives you a powerful map of common human tendencies. Financial psychology helps you understand the personal terrain on which those tendencies take hold.
What Behavioral Finance Explains Well
Behavioral finance is especially helpful when a financial decision is shaped by predictable cognitive bias. These patterns are not signs of low intelligence. They are efficient mental shortcuts that can become costly in situations involving uncertainty, risk, and emotion.
For example, anchoring can make you fixate on the price you paid for a stock, as if that number determines what the investment is worth now. Herd behavior can pull you toward whatever colleagues, headlines, or social media personalities are excited about. Mental accounting can lead you to treat a tax refund as “fun money” while carrying high-interest debt, even though dollars do not arrive with different responsibilities attached.
This lens is practical because it encourages better decision design. Automating retirement contributions can reduce the chance that short-term moods interrupt long-term saving. Creating investment rules before volatility hits can limit panic-driven trades. Waiting 24 hours before a nonessential purchase can soften the force of urgency and scarcity.
The strength of behavioral finance is that it does not require you to become perfectly rational. It helps you build guardrails around the moments when being human is most expensive.
Its limitation is that a bias label can become the end of the conversation. Calling a purchase “present bias” may be accurate, but it does not necessarily explain why buying something now feels more comforting than protecting your future self. It identifies the pattern. It may not reveal the need the pattern is trying to meet.
What Financial Psychology Sees Beneath the Behavior
Financial psychology treats money behavior as meaningful. That does not mean every costly habit is healthy or should be excused. It means behavior often has an emotional logic, even when it conflicts with your stated goals.
A person who spends after a difficult week may not simply lack discipline. Spending may offer relief, reward, control, or a temporary sense of possibility. Someone who never invests may not merely be risk-averse. They may equate financial caution with being a responsible adult, especially if they watched a parent struggle with debt or unpredictable income. Someone who constantly checks their account balance may be seeking certainty, not information.
This is where financial archetypes can be useful. An archetype is not a permanent label or a diagnosis. It is a framework for recognizing the role money tends to play in your inner life. One person may approach money as a protector and prioritize safety above growth. Another may see it as a source of freedom and resist systems that feel restrictive. A third may use achievement and income as evidence of worth, making rest or generosity feel surprisingly difficult.
At The Money Story, the purpose of identifying patterns like these is not to put people in boxes. It is to give them language for choices that have felt automatic. Once you can name the emotional job money has been doing, you can choose healthier ways to meet that need.
Financial psychology is particularly valuable when you have tried sensible tactics repeatedly and still cannot sustain them. The issue may not be the tactic. A budget can fail because it feels like deprivation. A savings goal can fail because the future does not feel emotionally real. A raise can disappear because higher income activates a long-held belief that success must be visible.
The Best Question Depends on the Problem
There are times when a behavioral finance approach is enough. If you tend to make unplanned online purchases late at night, removing saved payment details and setting a purchase threshold may solve a meaningful part of the problem. You do not need to excavate your entire money history to make a useful adjustment.
Other situations call for deeper reflection. If you set up those barriers, break through them, feel ashamed, and repeat the cycle, the pattern deserves more curiosity. What feeling arrives before the spending? What does the purchase promise? What story do you tell yourself afterward? The answers can reveal whether the behavior is connected to stress, belonging, self-worth, fear, or unresolved scarcity.
The same applies to investing. A written investment policy can protect you from common biases. But if every market decline sends you into a spiral, a spreadsheet alone may not restore confidence. You may need to separate the ordinary uncertainty of investing from the personal meaning you assign to uncertainty.
This is the trade-off: behavioral tools are often faster and easier to implement, while psychological work can create more durable change when a pattern is rooted in identity or emotion. The most effective approach is usually not either-or. It is behavior design supported by self-awareness.
How to Use Both Lenses in Everyday Money Decisions
Start by observing one recurring money moment without trying to fix it immediately. It might be avoiding bills, over-researching purchases, lending money you cannot afford to lend, or feeling guilty whenever you spend on yourself. Describe the behavior in plain language.
Then ask two sets of questions. The behavioral finance questions are: What bias, trigger, or environment might be influencing this choice? What friction, rule, or default would make the better choice easier? The financial psychology questions are: What emotion is present? What belief about money, safety, success, or deservingness is being protected? When did this pattern become familiar?
For instance, if you delay contributing to retirement, the behavioral answer may be present bias: immediate needs feel more compelling than a distant future. A useful intervention could be automatic contributions that increase when your pay increases. The psychological answer may be that planning far ahead feels impossible because you have learned not to trust stability. In that case, small automatic contributions matter not only because they save money, but because they help you practice a new relationship with the future.
Keep the first experiment small. Dramatic financial overhauls often trigger the same resistance they are meant to solve. Choose one action that respects your current reality: transfer a modest amount on payday, set a 48-hour pause for purchases over a chosen amount, or schedule a weekly ten-minute money check-in that does not require judgment.
Then notice what happens internally. If the action creates relief, resistance, resentment, pride, or anxiety, that response is data. Your emotions are not always instructions, but they are often information.
From Better Decisions to a Different Money Story
Behavioral finance can help you recognize the traps built into human decision-making. Financial psychology can help you understand why certain traps have such a strong pull on you. Together, they replace the unhelpful question, “What is wrong with me?” with a more useful one: “What pattern am I repeating, and what is it trying to do for me?”
That shift matters because shame rarely creates lasting financial change. Awareness, compassionate honesty, and well-designed action do. Your next money decision does not need to prove that you are disciplined enough or knowledgeable enough. It can simply be a small vote for the story you want your money to support.